From the Blog
Builder Incentives in San Antonio in 2026: Rate Buydowns, Closing Cost Credits, and the Fine Print
In September 2026, 66% of U.S. builders reported using sales incentives, according to the NAHB and Wells Fargo Housing Market Index, up from 63% in August, and Realtor.com found that nearly 1 in 5 new-construction listings advertised an incentive, with reduced mortgage rates the most common. In San Antonio, that shows up as rate buydowns, closing cost credits, and upgrade packages. Here is what builders are offering, what the fine print actually says, and how to compare it honestly.
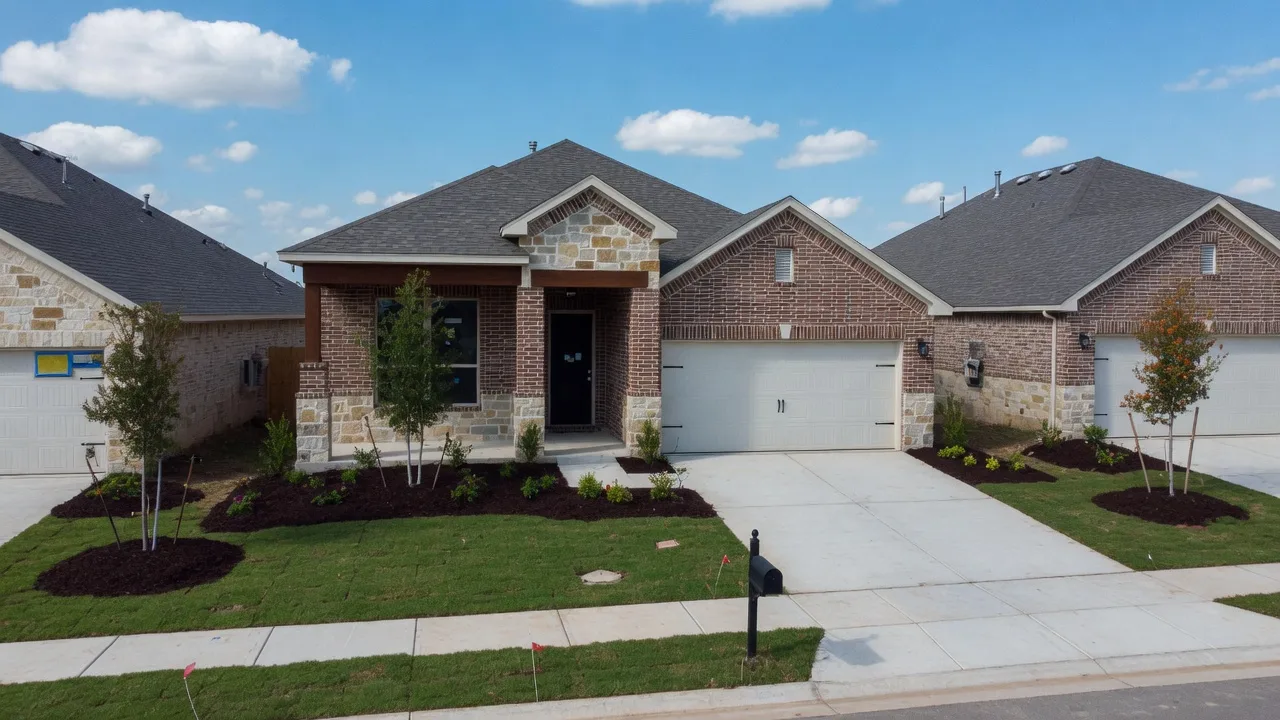
In September 2026, 66% of U.S. builders reported using sales incentives, according to the NAHB and Wells Fargo Housing Market Index, up from 63% in August, and Realtor.com found that nearly 1 in 5 new-construction listings advertised an incentive, with reduced mortgage rates the most common. In San Antonio, that shows up as rate buydowns, closing cost credits, and upgrade packages. Here is what builders are offering, what the fine print actually says, and how to compare it honestly.
This is the video I send every new-construction buyer; it pairs with the fine print below.
On my channel: Nobody Warns You About New Construction San Antonio Until It's Too Late
How common incentives really are
The NAHB and Wells Fargo Housing Market Index found 66% of U.S. builders using sales incentives in September 2026, up from 63% in August, with 38% cutting prices by an average of 6%. Realtor.com's August review of new-construction listings found 18.8% advertised an incentive, and by far the most common was a reduced mortgage rate, on 13.8% of listings. In San Antonio specifically, rate buydowns are the most popular incentive right now, and closing cost contributions typically run 2% to 6% of the purchase price. This is a market where builders are competing on terms, not just floor plans.
What San Antonio builders have been offering
Recent promotions show the range. M/I Homes ran a 3/2/1 buydown with year-one rates as low as 1.875% (5.6328% APR) on quick move-in homes closing by August 31, 2026, plus up to $7,500 in paid closing costs through its lender, free patios, and half-off lot premiums. Lennar ran temporary buydowns with year-one rates like 1.75%, up to $5,000 toward closing costs, up to $20,000 in price reductions in August, and a promotional 3.99% FHA fixed rate across the greater San Antonio area. These are snapshots of recent offers, and current incentives change monthly, so the question to ask is always what is live today, in writing.
The fine print that changes the value
Incentives are almost always tied to using the builder's preferred lender and to closing by a specific deadline, and that is where the value can shift. A buydown lowers the payment for the first few years, but the price stays where it is, and the market value of the home is what the appraisal and your future resale see. The APR tells you the true cost of the loan after the buydown, and the base price before the incentive tells you what you are actually paying for the house. Read both, plus the deadline, before you count the savings.
How to compare a buydown honestly
Run the buydown's year-one, year-two, and year-three payments against the standard-rate payment, then add up the difference over three years. A $20,000 price reduction is real equity you keep, while a buydown is a payment subsidy that ends, so compare the all-in price, not just the first-year payment. The honest question is not what the payment is in year one, but what the home is worth and what the payment will be for the life of the loan. That comparison, against resale comps on the same street, is the one that decides the deal.
The questions to ask before you sign
Ask these in writing: Is the incentive tied to your preferred lender, and what happens if I bring my own? What is the APR after the buydown, and what is the base price before the incentive? What does the recent appraisal data say the home is worth? What happens to the incentive if I miss the closing deadline? And what HOA, MUD, or community fees are not on the price sheet? None of these questions is aggressive; they are exactly what a careful buyer asks, and a good builder answers them happily.
When a builder incentive is genuinely good
A builder incentive is a good deal when the base price is already fair against resale comps, when you would use the preferred lender anyway, and when the buydown gets you to a payment you can sustain for the long term. It is a bad deal when it dresses up an overpriced base or locks you into a loan you would not otherwise choose. My new-construction guides cover the mistakes and the communities, and the same rule runs through all of them: compare the all-in price and the long-term payment, then decide.
Written by Phyllis Domingo
REALTOR® · TX License 745926 · 100+ homes sold · Helping families move well in San Antonio and the Hill Country since long before the hard part became normal.
Have a question about this topic?
Every family's situation is different. Send me a note and I will respond personally, usually within a business day.