From the Blog
Homeowners Insurance in San Antonio: The Hidden $3,000
When out-of-state buyers run their first Texas budget, homeowners insurance is the line item that surprises them most. The San Antonio-New Braunfels metro averaged about $2,948 a year for a typical homeowners policy in 2025, roughly $291 more than the national average, and analysts project it rising to about $3,048 by the end of 2026. Here is why Texas insurance costs what it costs, what drives your personal rate, and how to plan for it.
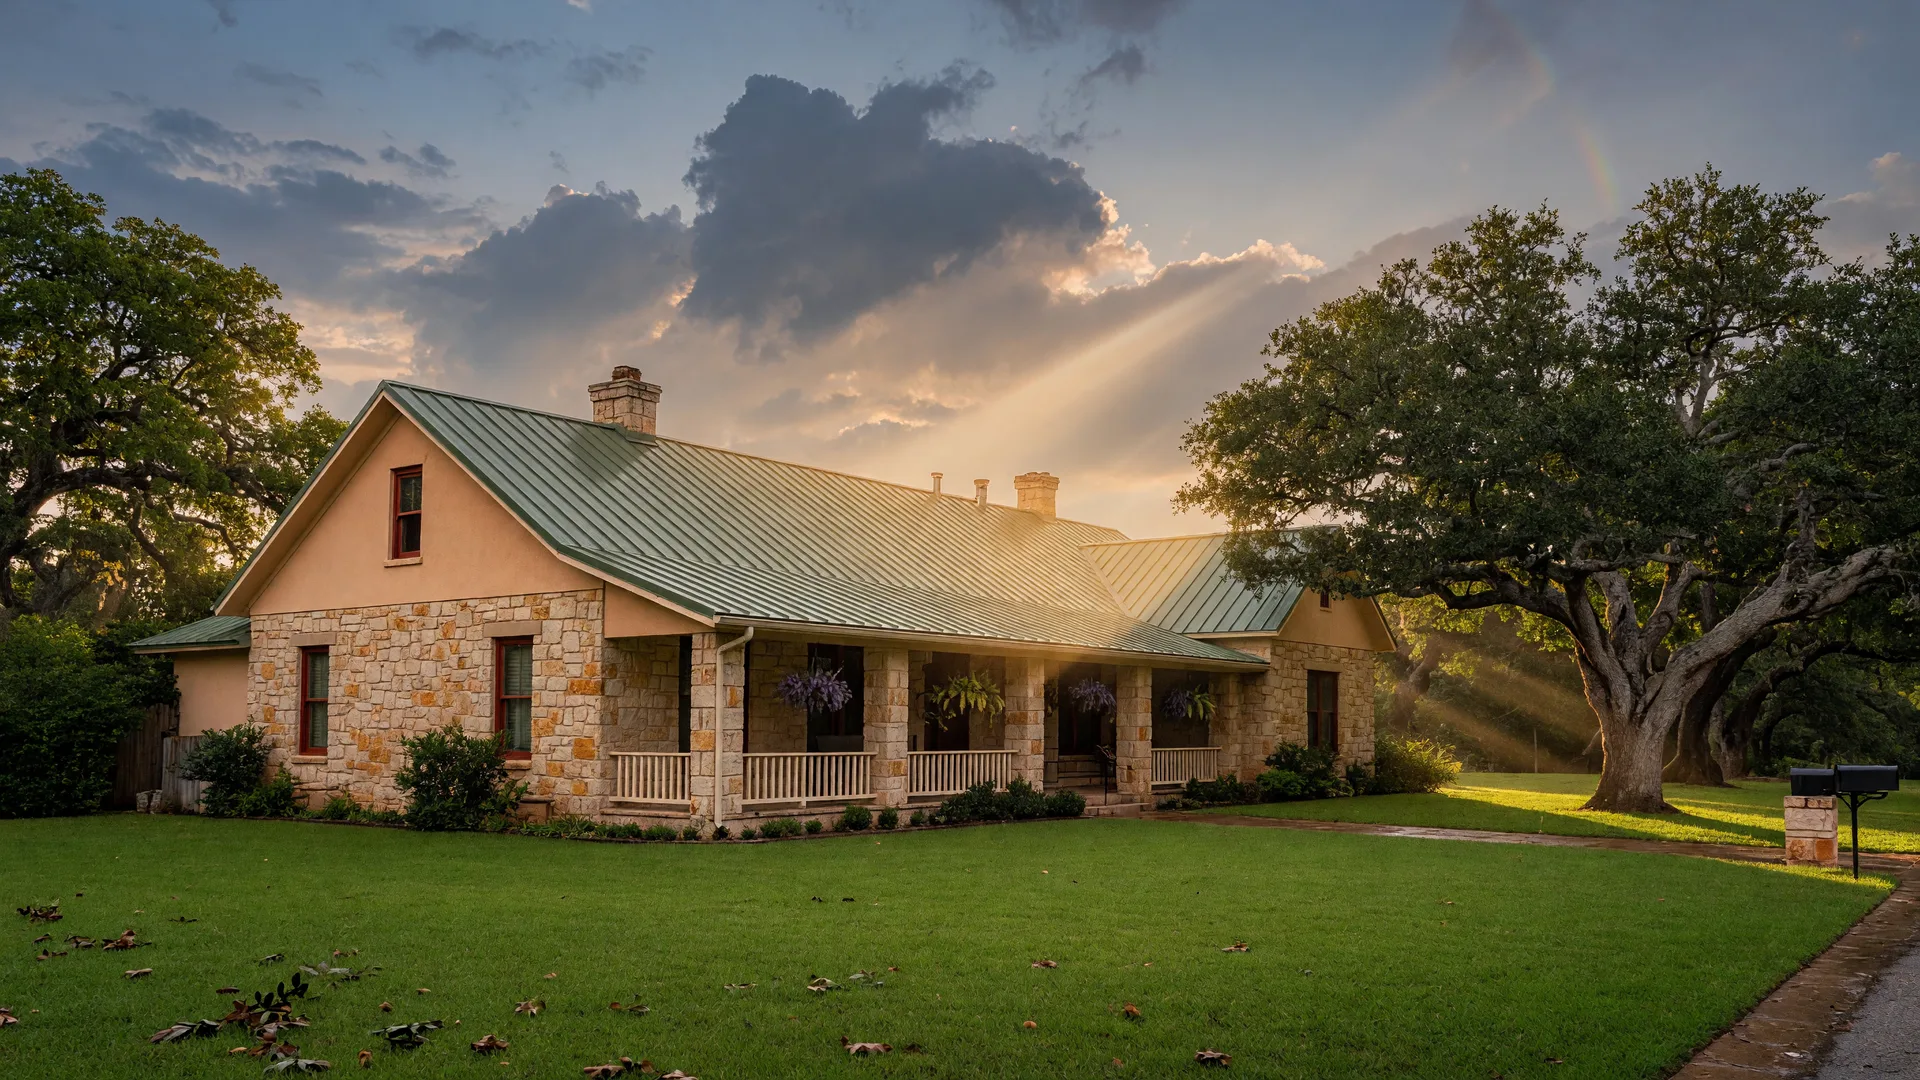
When out-of-state buyers run their first Texas budget, homeowners insurance is the line item that surprises them most. The San Antonio-New Braunfels metro averaged about $2,948 a year for a typical homeowners policy in 2025, roughly $291 more than the national average, and analysts project it rising to about $3,048 by the end of 2026. Here is why Texas insurance costs what it costs, what drives your personal rate, and how to plan for it.
On my channel: Cost of Living in San Antonio Texas: Property Taxes, Homeowners Insurance & Utilities
What the average actually is
The San Antonio metro averaged about $2,948 a year in 2025, with projections of a rise of roughly 3.4% to about $3,048 by the end of 2026, which puts San Antonio on the lower end for Texas metros. That is one of the honest positives. But it is still about $291 above the national average of roughly $2,575 to $2,600, and the state as a whole is a different story: Texas premiums average around $4,085 to $4,644 a year depending on the source, and LendingTree ranks Texas among the five most expensive states for home insurance.
Why Texas rates run high
Hail, wind, and severe thunderstorms do more than dent roofs, they drive claims, and Texas leads the country in hail losses year after year. Insurers price that risk into every policy, and reinsurance costs push premiums higher for everyone. Texas also saw premiums climb roughly 56% since 2020, which is why even long-time locals notice the jump at renewal time.
What moves your personal rate
Your exact number depends on your roof age and material, your home's age and construction, your claims history, your credit score, your deductible, and the ZIP code's storm history. A 20-year-old roof will cost you at closing and in insurance. Newer metal or impact-resistant roofs, higher deductibles, and bundling with auto coverage are the levers buyers actually control. This is why I always tell buyers to price insurance before they make an offer, not after.
The buyer's workflow
Before you make an offer, run a homeowners insurance quote for that exact address the way you run a property tax estimate. Lenders require insurance, typically for at least the loan amount or the replacement cost, and the premium lands in your escrow and shows up in your monthly payment. Two similar homes can carry very different premiums, so treat insurance as part of the honest monthly math, not an afterthought.
What this means for your budget
Add roughly $2,950 to $3,100 a year to your housing picture for the San Antonio average case, and more if the home is older, the roof is older, or the neighborhood has a storm record. On a $350,000 home with 20% down, that is close to $245 to $260 a month alongside your mortgage and property taxes. Most relocating families tell me the surprise fades once they see the number up front, and that is exactly why I put it in front of them.
Written by Phyllis Domingo
REALTOR® · TX License 745926 · 100+ homes sold · Helping families move well in San Antonio and the Hill Country since long before the hard part became normal.
Have a question about this topic?
Every family's situation is different. Send me a note and I will respond personally, usually within a business day.